

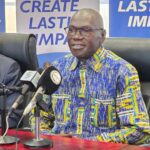


The Zambian Government has called for closer collaboration between governance and internal audit professionals, saying the complex challenges facing modern institutions can no longer be addressed through isolated approaches. Ministry of Information and Media Permanent Secretary Thabo Kawana said the two professions must break down institutional silos and work together to strengthen integrity, accountability and effective decision-making. He said institutions need integrated leadership and coordinated action to remain efficient, transparent and responsive to changing demands. Kawana was speaking in Livingstone at the first joint governance forum and annual audit conference, which runs through Friday. His message places good governance and effective internal auditing at the centre of efforts to build stronger institutions and support sustainable economic growth under the Grow Zambia Agenda.
Kawana said governance professionals and internal auditors have responsibilities that increasingly overlap in the modern institutional environment. Public and private organisations face financial, technological, regulatory and operational risks that can affect their ability to deliver services and achieve their objectives. These challenges require different professional teams to share information and work toward common solutions instead of operating within separate institutional structures. Collaboration can help organisations identify problems earlier and develop coordinated responses to risks. It can also strengthen accountability by ensuring that governance principles are reflected in everyday decisions and operations.
The Permanent Secretary stressed that good governance should not be viewed simply as a requirement for meeting rules and regulations. He described it as a mechanism for building trust between institutions and citizens. Public confidence can be affected by how institutions manage resources, communicate information and respond to concerns. Transparent decision-making and consistent accountability can help citizens understand how institutions operate and how public resources are managed. Strong governance therefore has implications for both institutional performance and the relationship between government institutions and the people they serve.
Kawana said sustainable economic growth depends on institutions that are efficient, transparent and responsive. Economic development requires institutions to make decisions, manage resources and implement programmes effectively. Weak systems can create delays, increase risks and reduce confidence among citizens, businesses and potential investors. Strong governance provides structures for accountability while helping institutions maintain clear responsibilities and reliable processes. This makes institutional performance an important part of the broader economic environment in which investment and development take place.
The relationship between governance and investment was also central to Kawana’s remarks. He argued that economic growth and investment require institutions where accountability and governance systems function effectively. Investors and other economic actors need confidence that institutions can operate predictably and that established rules will be applied consistently. Public institutions also need strong controls to ensure that resources are used for their intended purposes. Effective governance can therefore support an environment in which economic activity and public development programmes can operate with greater institutional confidence.
Internal auditors have an important role within this framework because their responsibilities extend beyond examining financial transactions. Kawana noted that the profession has evolved into a strategic advisory function that helps organisations anticipate risks, strengthen internal controls and create value. Internal auditors can provide management with information about weaknesses in processes and areas where controls may need improvement. Their work can also help institutions prepare for risks before those risks develop into major operational problems. This broader role makes internal audit an important component of institutional risk management and organisational improvement.
The changing role of internal auditors reflects the increasingly complex environment in which organisations operate. Auditors must consider not only financial controls but also technology, cybersecurity, data management, regulatory requirements and operational risks. Organisations also need systems that can respond quickly when circumstances change. Internal audit professionals can contribute by assessing whether existing controls remain appropriate as institutions introduce new systems and processes. Their work can help management understand emerging risks while supporting stronger accountability across the organisation.
Technology was another major issue raised at the conference, particularly the growing use of artificial intelligence. Kawana urged internal auditors to remain agile and adapt to emerging technologies that are changing governance, compliance and assurance systems. Artificial intelligence can affect how organisations process information, identify patterns and assess risks. At the same time, the use of AI creates new questions around data quality, security, transparency, accountability and human oversight. Auditors and governance professionals therefore need to understand these technologies and consider how their use affects institutional controls and decision-making.
The adoption of AI means governance and audit professionals will need to develop new skills and approaches. Traditional audit methods may not always provide sufficient insight into systems that use automated decision-making or large-scale data analysis. Professionals will need to understand how digital systems operate and how organisations can maintain appropriate controls around their use. They must also consider whether information produced by automated systems is accurate, reliable and properly managed. Continuous professional development will therefore remain important as technology changes the nature of governance and assurance work.
Breaking down institutional silos can also improve the flow of information within organisations. Governance teams, internal auditors and management often work with different types of information, but effective decision-making depends on connecting those perspectives. When information remains confined to individual departments, organisations can miss important warning signs or duplicate efforts. Collaboration can create a clearer picture of institutional risks and help different teams coordinate their responses. It can also support a stronger culture of accountability because responsibilities and expectations become easier to understand across an organisation.
Kawana’s comments also connect institutional accountability with the wider national development agenda. The Government has placed transformation, accountability and economic growth at the centre of the Grow Zambia Agenda. Achieving these objectives requires institutions that can implement policies effectively and manage resources responsibly. Governance systems provide a framework for setting responsibilities and maintaining transparency, while internal audit can provide assurance about the effectiveness of controls and risk management. Together, these functions can contribute to stronger institutional capacity as Zambia pursues its development priorities.
The message that growth does not happen by accident highlights the importance of institutional foundations in economic development. Economic growth requires investment, effective policies, functioning institutions and the capacity to implement decisions. Accountability also matters because institutions need mechanisms that identify weaknesses and encourage corrective action. Internal audit can contribute to this process by providing independent assessments of risks and controls within its organisational mandate. Governance professionals can complement that work by helping institutions maintain structures and practices that support transparency, integrity and responsible decision-making.
The joint governance forum and annual audit conference in Livingstone provides an opportunity for professionals from the two fields to examine these issues together. Bringing governance and audit practitioners into the same forum can encourage discussion about shared challenges and practical approaches to institutional improvement. The conference also creates space to consider how technology is changing professional responsibilities and how organisations can prepare for emerging risks. The emphasis on collaboration reflects the need for institutions to move beyond narrow departmental approaches. It also reinforces the idea that accountability is a shared institutional responsibility rather than the responsibility of a single professional group.
Strong governance and internal audit systems can support public institutions as they respond to rapidly changing demands. Government departments must manage public resources, communicate information accurately and deliver services while dealing with changing economic and technological conditions. Effective controls can help reduce operational risks while transparent governance can strengthen public confidence. Internal auditors can provide management with information about areas requiring attention, while governance professionals can support structures that promote accountability and ethical conduct. These functions become increasingly important as institutions take on more complex responsibilities.
The emphasis on accurate information is also significant for public administration. Citizens depend on institutions to provide clear and reliable information about policies, programmes and public services. Internal systems also depend on accurate information because managers need reliable data when making decisions and monitoring performance. Weak information flows can make it harder to identify problems or measure whether programmes are achieving their objectives. Strong governance and audit processes can help organisations improve the reliability, transparency and accountability of information used in decision-making.
Kawana’s call for greater collaboration ultimately points to a broader shift in how institutions approach governance and internal audit. Neither function can operate effectively in isolation when organisations face interconnected financial, operational, technological and regulatory risks. Stronger cooperation can help institutions anticipate challenges, improve internal controls and make better-informed decisions. The growing influence of artificial intelligence also means professionals must continue developing their skills and adapting established practices to new technologies. For Zambia’s Grow Zambia Agenda, building institutions that are accountable, transparent, responsive and capable of managing emerging risks will remain an important part of creating the conditions for sustainable economic growth and public trust.